Structural Definition and Scope of the Portable Dishwasher Market
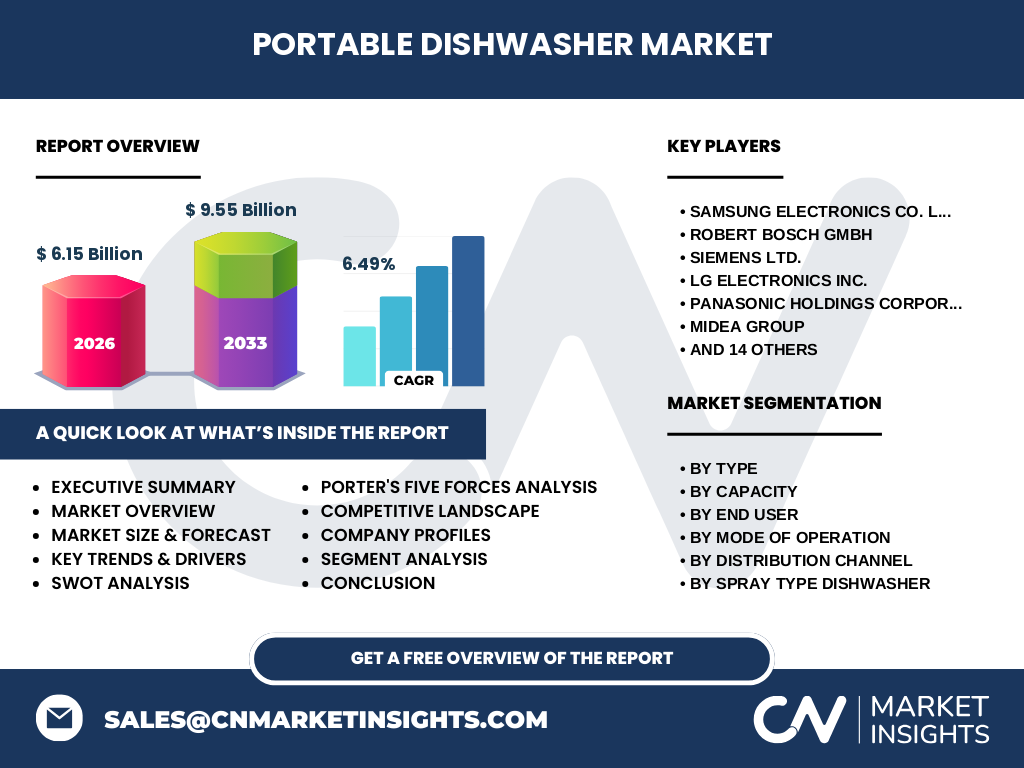
Our analysis indicates the Portable Dishwasher Market encompasses flexible cleaning appliances engineered for urban housing constraints. Valued at $6.15 Billion in 2026, this sector includes spray and ultrasonic units navigating strict UL and Energy Star compliance standards across global metropolitan trade nodes.
What core drivers, restraints, and opportunities shape the Portable Dishwasher Market?
Urbanization and shrinking kitchen footprints serve as primary catalysts, while high stainless steel raw material costs act as restraints. Strategic opportunities emerge in developing compact 5-10 Place Settings configurations tailored for rental properties and multi-family residential developments.
Emerging Trends and Growth Patterns in Appliance Engineering
Industry trends highlight a rapid pivot toward water-efficient Ultrasonic Type Dishwasher models. Manufacturers like Midea Group and Haier Group Corporation leverage IoT integration to capture market share among tech-savvy urban consumers seeking resource-saving smart home appliances.
COVID-19 Impact Analysis and Market Recovery Trajectory
The pandemic severely disrupted global supply chains originating from major Asian manufacturing hubs, causing severe logistical bottlenecks at ports like Los Angeles and Ningbo. Recovery was accelerated by home-renovation booms, driving unprecedented demand for easily installable countertop units.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately high, dominated by conglomerates such as Samsung Electronics Co. Ltd., Robert Bosch GmbH, and LG Electronics Inc. These Tier-1 players utilize aggressive distribution networks across e-commerce platforms to outpace regional manufacturing competitors.
Executive Summary of the Portable Dishwasher Market Industry Trends
Our research confirms the Portable Dishwasher Market is entering a high-growth phase. Driven by changing lifestyle demographics and spatial constraints, the industry is poised for sustained expansion underpinned by continuous product innovation in automated cleaning modes.
Market Forecast and Valuation Trajectory Through 2033
Based on our econometric modeling, the market is projected to reach $9.55 Billion by 2033, expanding at a robust 6.49% CAGR. This trajectory reflects increasing consumer preference for flexible, non-permanent kitchen infrastructure globally.
Segmentation Analysis by Type, Capacity, and End Use
The market segments into spray and ultrasonic types, catering to residential and commercial buyers. Capacity tiers range from 5-10 Place Settings to above 15, with automatic and manual operational modes distributed via specialty stores and e-commerce channels.
Geographic Distribution and Regional Performance Analysis
North America and Europe currently dominate consumption due to high rental market densities, whereas Asia-Pacific exhibits the fastest regional growth rate, driven by rapid urbanization and rising disposable incomes across metropolitan centers in China and India.
In-Depth Regional Review of North America and Asia-Pacific
North American growth is anchored by appliance giants like Whirlpool Corporation responding to apartment living trends. Meanwhile, Asia-Pacific thrives on manufacturing output from Panasonic Holdings Corporation and Midea Group, satisfying surging domestic demand for compact dishwashing solutions.
Strategic Positioning of Leading Corporate Players
Firms like Electrolux AB and SMEG S.p.A. focus on premium aesthetic integration, whereas Danby Products Ltd. and Sunpentown International Inc. capture value through budget-friendly, high-durability portable units designed for tight spaces.
Porter's Five Forces Assessment of Competitive Pressures
Bargaining power of buyers remains high due to intense e-commerce price transparency. Threat of substitutes is moderate, counterbalanced by continuous innovations in ultrasonic cleaning technology introduced by specialized market participants.
SWOT Analysis of the Portable Dishwasher Market Landscape
Key strengths include high product versatility and easy installation. Weaknesses involve high initial unit costs relative to built-in models. Opportunities lie in emerging micro-apartment designs, while supply chain vulnerabilities remain a persistent threat.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying food-grade plastics and stainless steel. It flows through assembly plants operated by entities like LG Electronics Inc. and Panasonic, culminating in delivery via major retailers and digital platforms.
Investment Insights and High-Potential Growth Areas
Investors should prioritize manufacturers scaling Compact Or Portable Ultrasonic Dishwasher technologies. These segments yield higher operating margins and align with tightening global energy-efficiency mandates enforced by regulatory agencies.
Conclusion and Strategic Takeaways for Industry Stakeholders
Sustained success in this market requires agile supply chain management and continuous feature upgrades. Companies investing in automated, water-saving countertop configurations will capture disproportionate value through 2033.
Research Methodology and Baseline Estimation Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registries, primary stakeholder interviews with executives at firms like Asko Appliances AB, and macroeconomic indices tracking housing starts and retail sales.
Scope of the Report and Analytical Parameters
This report covers global revenue estimations from 2026 to 2033 across specified product segments and regional blocks. Limitations include fluctuating foreign exchange rates and unforeseen geopolitical trade policy adjustments impacting logistics.
Recent Developments, Partnerships, and Product Launches
Recent strategic moves feature major product launches by Samsung and Bosch emphasizing smart-connectivity. Industry partnerships focus on sustainable packaging and integrating IoT diagnostics to minimize post-purchase maintenance costs for residential end-users.